Louisiana Hurricane and Storm Damage Insurance Claims
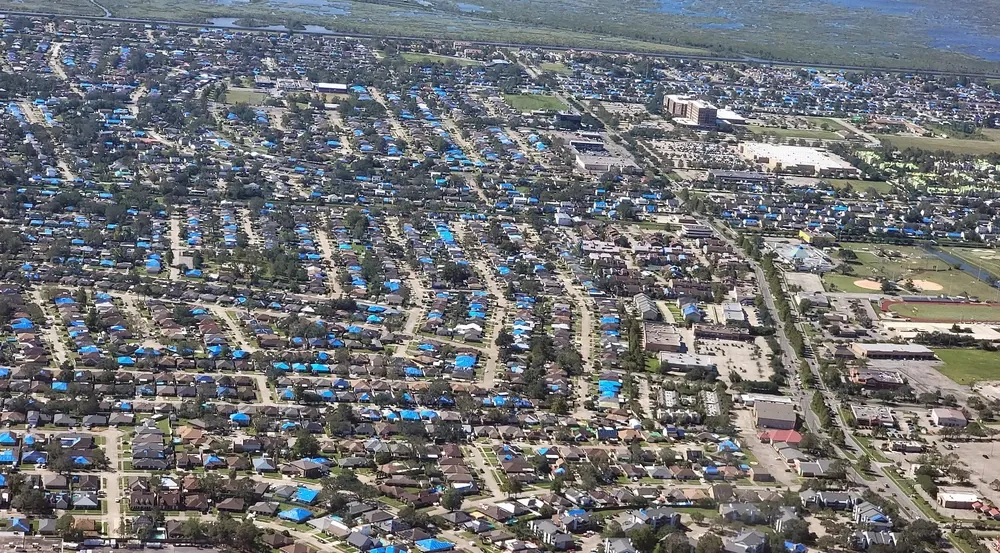
If a hurricane damaged your home or business and your insurer denied the claim, delayed it, or paid less than the repairs will cost, I can review it for free. I have handled Louisiana hurricane claims since 2005, from Katrina and Rita through Gustav, Ike, Laura, Ida and Francine.
What I see insurers do after a storm
After every major storm I see the same patterns:
- Low first estimates that leave out damage or price repairs below what local contractors charge.
- Shuffling adjusters, so you re-explain your claim and re-send documents again and again.
- Calling wind damage “flood” (or the reverse) to push the loss onto a policy that does not cover it.
- Holding back depreciation and contents payments long after repairs are under way.
- Slow responses that push you past the deadlines in your own policy.
How I work on your claim
I know the inspection process well. I’m trained on the estimating software most major insurers use, so I can read their estimates line by line and see what was left out or underpriced. For re-inspections, I bring in independent adjusters, roofers and contractors to document the full damage.
- Free claim review. We look at your policy, the insurer’s estimate and your photos.
- Re-inspection. Independent experts re-inspect the property and document what the insurer missed.
- Claim presentation. We prepare the proof of loss, the estimate and supporting documents.
- Demand and negotiation. We press for full payment, plus penalties where the law allows.
- Appraisal, mediation or suit if the insurer still will not pay fairly.
Deadlines matter
Your policy sets deadlines to report the loss, submit proof of loss, and file suit. Louisiana law does not allow a homeowners policy, or most other property policies, to limit your right to sue to less than 24 months from the date of the loss (La. R.S. 22:868(B)), and your policy may allow more. For catastrophic losses, you must also give the insurer 60 days’ written notice before suing for penalties under the catastrophe statute. If your storm was more than a year ago, call now so we can check your dates.
Claims I handle
- Wind and roof damage, including hurricane deductibles
- Hurricane flood claims
- Depreciation and holdback
- Business interruption
- Bad faith penalties
- Loss of use, mold, condo and insolvent-insurer questions
Storms
- Hurricane Francine (2024)
- Hurricane Ida (2021)
- Past storms: Katrina, Rita, Gustav, Ike, Laura, Delta and Zeta
Guides
- Hurricane claim guide: from the storm to the adjuster’s visit
- Mediation and appraisal
- Hurricane claim FAQ
Published decisions
- Pitts v. Louisiana Citizens Property Insurance Corp., 4 So. 3d 107 (La. App. 4 Cir. 2009): a class action kept a Katrina homeowner’s claim timely. Read more.
- Express Rent-A-Car v. U-Save (E.D. La. 2009): a group “self-insured” program is an insurer under Louisiana’s bad-faith statutes. Read more.
What a client said
“The Lavis Law firm assisted me with a hurricane IDA claim against a large insurance company. His expertise and persistence against the bad faith tactics, produced the results my wife and I needed to restore our home. I wouldn’t hesitate to call Charles Lavis for my future legal needs.”
— Blain W., Google review
Past results do not guarantee a similar outcome.
Talk to me about your claim
New Orleans: 643 Magazine St #301D, New Orleans, LA 70130 · 504-834-4000
Baton Rouge: (225) 343-0444 · Toll free: 866-558-9151
We can meet at your property, at the office, or by video or phone.