Past Louisiana Hurricanes: Katrina to Zeta
I began handling hurricane insurance claims after Katrina in 2005. The lessons from those years still shape how I handle claims today.
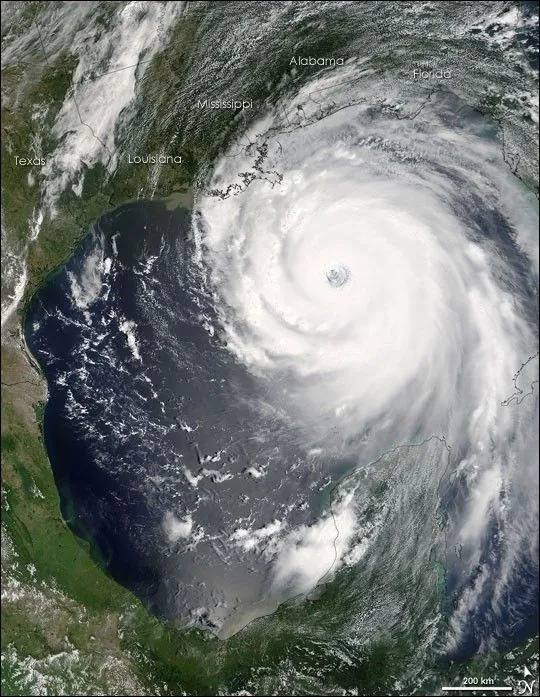
| Storm | Louisiana landfall | Strength | What it did |
|---|---|---|---|
| Katrina | Aug. 29, 2005, near Buras | Category 3, about 125 mph | 15–19 ft surge; levee and floodwall failures flooded about 80% of New Orleans |
| Rita | Sept. 24, 2005, at the Louisiana–Texas line | Category 3, about 115 mph | About 15 ft surge destroyed nearly every structure in Cameron Parish |
| Gustav | Sept. 1, 2008, near Cocodrie | Category 2, about 105 mph | 12–13 ft surge in the delta; overtopped levees and floodwalls in parts of metro New Orleans |
| Ike | Galveston, Texas, Sept. 13, 2008 (no Louisiana landfall) | Category 2 | 10–13 ft surge in southwest Louisiana, pushing inland near Lake Charles |
A Katrina case: a class action kept a homeowner’s claim alive
In Pitts v. Louisiana Citizens Property Insurance Corp., 2008-CA-1024 (La. App. 4 Cir. 1/7/09), 4 So. 3d 107, I represented a New Orleans homeowner whose Katrina claim was badly underpaid. Her claim had been covered by pending class actions. When one class was certified without underpayment claims, she filed her own suit. The trial court dismissed it as too late.
The Fourth Circuit reversed. A pending class action suspends the deadline for everyone in the proposed class. For someone later excluded from the class, the deadline starts running again 30 days after notice of the exclusion (La. C.C.P. art. 596). She filed before that notice, so her claim was timely. The Louisiana Supreme Court denied review.
The lesson today: a deadline that looks expired may not be. Have a lawyer check before you give up on a claim.
What Katrina taught us
- Wind versus water. Katrina claims turned on whether wind or flood caused the damage. That fight still happens after every storm.
- Deadlines can change. In 2006, Act 739 extended the time to file Katrina and Rita claims with insurers. Act 802 extended the time to sue, to August 30, 2007 for Katrina and September 25, 2007 for Rita. The Louisiana Supreme Court upheld both.
- Insurers of last resort underpay too. Louisiana Citizens, the state’s insurer of last resort, faced class actions over late and low Katrina payments.
Past results do not guarantee a similar outcome.
The 2020 season: Laura, Delta and Zeta
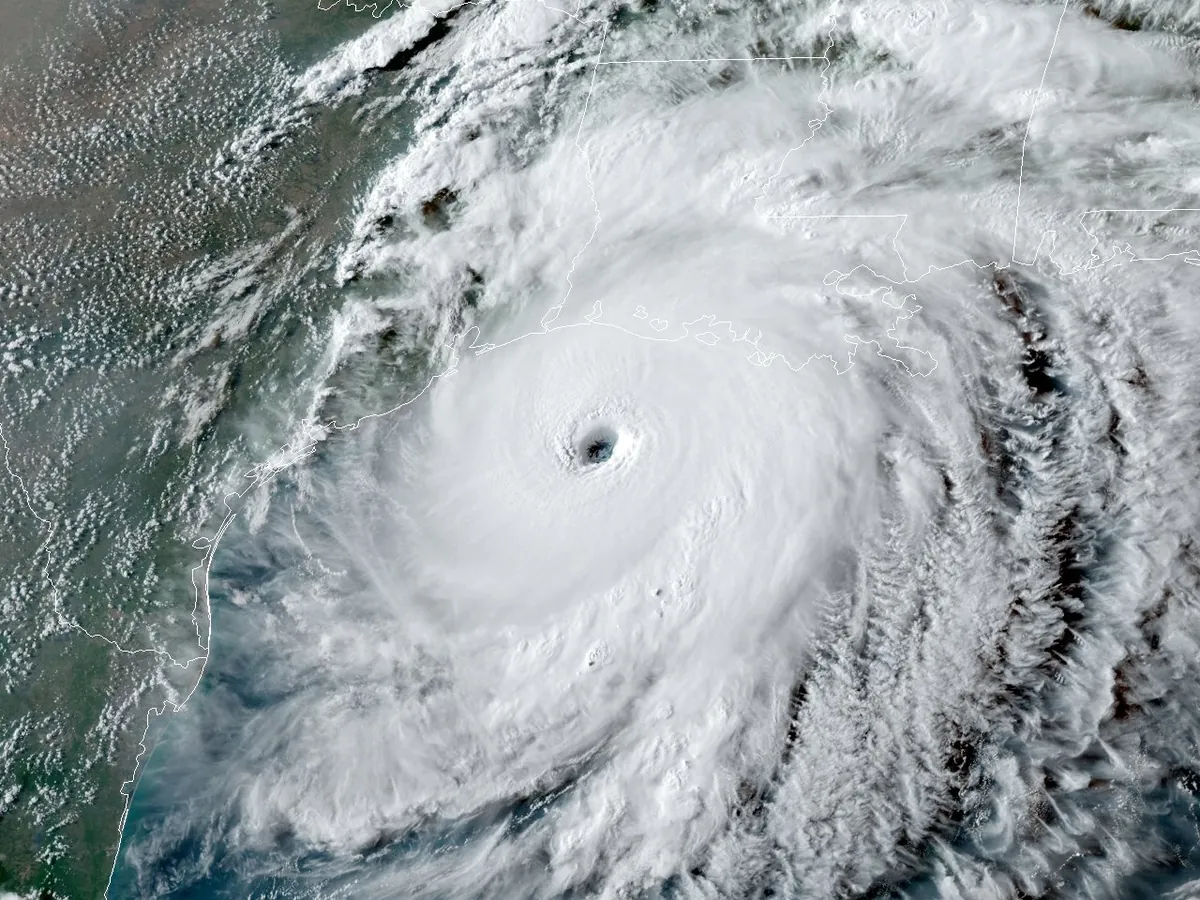
In 2020, three hurricanes struck Louisiana in nine weeks:
| Storm | Landfall | Strength at landfall | Hardest hit |
|---|---|---|---|
| Laura | Aug. 27, 2020, near Cameron | Category 4, about 150 mph | Cameron and Calcasieu; 12–18 ft surge, Lake Charles flooded |
| Delta | Oct. 9, 2020, near Creole | Category 2, about 100 mph | Southwest Louisiana again; temporary roofs from Laura blown off |
| Zeta | Oct. 28, 2020, near Cocodrie | Category 3, about 115 mph | Grand Isle levee breached; wind damage in Orleans, Jefferson, St. Bernard, Plaquemines |
Two storms, one deductible
Many Lake Charles homeowners were hit by both Laura and Delta. On covered homeowners policies, Louisiana law applies a separate hurricane or named-storm deductible on a calendar-year basis (La. R.S. 22:1337). For the second storm, the insurer may apply the greater of the unused hurricane deductible or your deductible for other perils. You generally should not pay the full hurricane deductible twice in the same year.
When the second storm hits a damaged house
Delta tore off tarps and temporary roofs before Laura repairs were done. Insurers then argued over which storm caused which damage. Photos and dated repair records from after the first storm are what settle that argument.
Insurers that failed
Several insurers that wrote Laura and Delta policies later became insolvent, and their claims moved to LIGA. See Hurricane claim FAQ.
Are 2020 claims still open?
The 24-month minimum suit deadline for these storms passed in 2022, but your policy may allow longer. If you have a 2020 claim still in dispute, call so we can check whether anything remains.
Talk to an attorney who has handled storm claims since 2005: 504-834-4000. Back to Louisiana Hurricane Insurance Claims